Quick Summary
Handling insurance roof claims starts with a careful inspection and protecting the home from further harm, then documenting storm damage with photos, a storm date record, and a professional roofing report. File promptly, read your policy’s depreciation, deductible and matching terms, and dispute any shortfall with a written supplement, reinspection, or appraisal.
- Storm damage is often missed from the ground, so inspect the outside of the home for cracked shingles, dented gutters and bent vents.
- Take wide and close-up photos, including a coin or ruler beside small damage, and record the storm date.
- File as soon as possible, since most policies set time limits for reporting storm damage.
- Budget for the depreciation holdback on replacement cost policies and keep every receipt.
- Submit a written supplement listing omitted items when the insurer’s estimate falls short of your contractor’s.
Table of Contents
- Step 1: Assess Roof Damage and Protect the Home From Further Harm
- Step 2: How to Document Roof Storm Damage for Insurance Claims
- Step 3: Filing the Claim and Understanding Your Policy and Deadlines
- Step 4: What Not to Say to an Insurance Adjuster About Roof Damage
- Step 5: What to Do If Your Denied Roof Insurance Claim Is Denied or Underpaid
- Booking a Free Roof Inspection and Claim Support Review With Atlanta Roof ProZ
- Frequently Asked Questions
Step 1: Assess Roof Damage and Protect the Home From Further Harm
Storm damage is often easy to miss from the ground: hail and wind can crack shingles, loosen flashing, and dent vents without obvious mess.
Walk around the outside of the home. Look for missing or cracked shingles, dented gutters and downspouts, bent metal vents, and granules piling up in the gutters.
Then protect the home from further harm.
Watch out: Don’t climb onto a damaged roof to inspect it yourself.
Step 2: How to Document Roof Storm Damage for Insurance Claims
Good documentation turns a storm into a supported claim. Your adjuster will rely on the evidence you bring to your insurance roof claims, so gather it early and keep it organized.
Photos, Video, and Storm Date Records
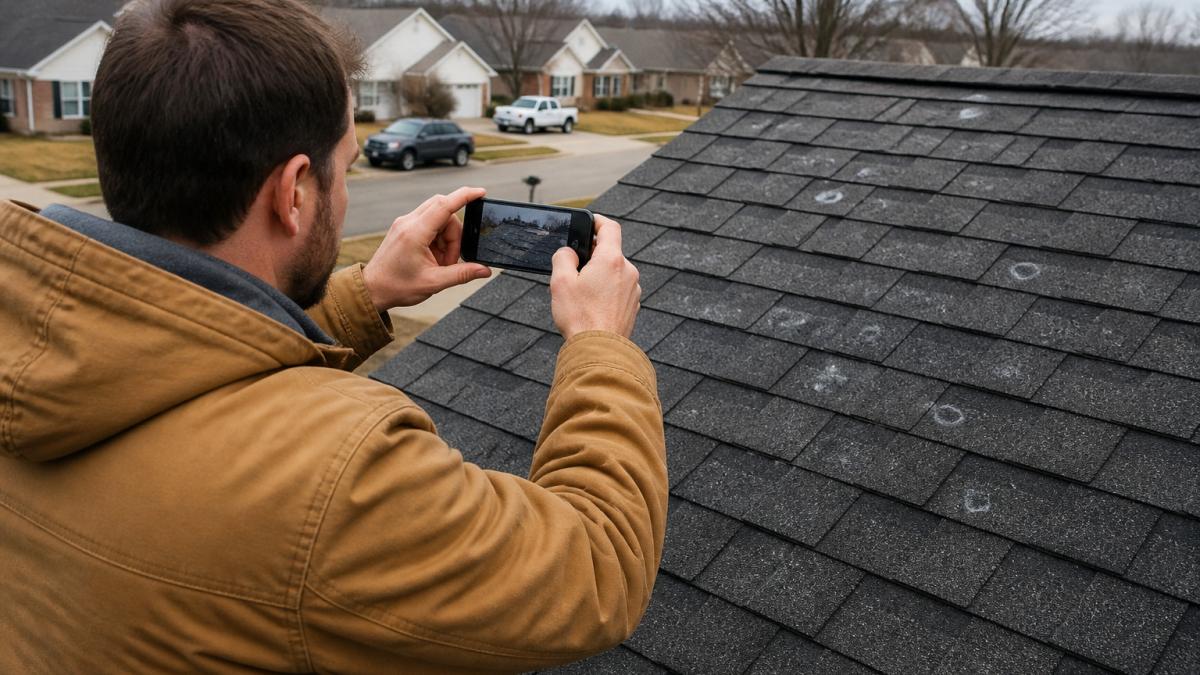
Take wide shots of each elevation, then close-ups of specific damage, including a dent or crack next to a coin or ruler so the size is clear.
Write down the storm date. Check local weather reports or National Weather Service storm history and save any printouts (Finding past weather…Fast). Note when you first noticed the damage and any interior leaks.
Getting a Professional Roof Inspection
A licensed roofing contractor can identify damage that homeowners often miss, such as bruised shingle mats and cracked flashing. Ask for a written inspection report with photos, measurements, and a description of each issue. Keep this report with your other claim documents.
Some insurers accept the contractor’s report as evidence; others send their own adjuster. Either way, a detailed inspection gives you a stronger starting point.
Step 3: Filing the Claim and Understanding Your Policy and Deadlines
Once your evidence is in order, file the claim as soon as possible. Most policies set time limits for reporting storm damage, and waiting can put coverage at risk.
Tell the insurer the date of loss, describe the damage, and list the protective steps you’ve taken.
Insurers typically have a set number of days to acknowledge a claim, inspect, and decide. Ask your adjuster for the expected timeline in writing.
Ask the adjuster to confirm three dates in writing: the date the claim was acknowledged, the date of the inspection, and the date a coverage decision is due. If any of those slip, you have a documented basis for a follow-up call.
Depreciation, Deductibles, and Policy Exclusions
Actual cash value vs. replacement cost. An actual cash value (ACV) policy pays the roof’s depreciated value before the storm, not replacement cost.
How depreciation is calculated. Adjusters apply a depreciation schedule based on roof age and expected service life, often straight-line: a 20-year shingle roof at 10 years old may be roughly half depreciated. Schedules vary by insurer, so ask the adjuster to show the depreciation line item on the estimate.
Deductibles. Your deductible is what you pay before insurance covers the rest.
Common exclusions to check. Read the exclusions for wear and tear, deterioration, poor maintenance, faulty workmanship, and whether cosmetic damage (hail dents that don’t affect function) is excluded.
Don’t sign a repair contract or authorize permanent work before the insurer’s inspection. Permanent repairs made before the adjuster documents the damage can complicate or reduce your settlement.
State insurance department consumer guides and complaint resources
The article’s key policy terms and what each one means for your payout:
| Term | What it means | Why it matters |
|---|---|---|
| Actual cash value (ACV) | Pre-storm depreciated value of the roof | Pays less than replacement cost |
| Replacement cost value (RCV) | Cost to install new materials of like kind and quality | Subject to limits |
| Depreciation holdback | Amount withheld until repairs are complete | Budget for it and keep receipts |
| Deductible | What you pay before insurance covers the rest | Check wind and hail deductibles separately |
| Matching | Repair or replace to match undamaged portion | Depends on policy language and state rules |
Step 4: What Not to Say to an Insurance Adjuster About Roof Damage
Your words during the inspection matter. Stick to verifiable facts and avoid guessing about causes or costs, speculation can narrow coverage later.
Don’t say the roof was “fine” before the storm if you haven’t checked, and don’t guess its age.
Focus on what happened and what you observed. Point out damage clearly, hand over your documentation, and let the adjuster reach conclusions after the inspection.
- Do say: “I noticed these dents after the storm on this date.”
- Don’t say: “This was definitely caused by the storm.”
- Do say: “I’ll send you the contractor’s report.”
- Don’t say: “The roof will need a full replacement, right?”
Step 5: What to Do If Your Denied Roof Insurance Claim Is Denied or Underpaid
A denied or low settlement isn’t always final. Read the denial letter closely and ask the insurer to explain in writing which policy terms it relied on, then compare that against your photos, the contractor’s report, and your policy. Most disputes come down to a missed scope item, a coverage interpretation, or a depreciation/matching disagreement, each with a different fix.
Supplementing an Incomplete Estimate
A supplement is a formal request to add work the original estimate left out. It’s the most common way homeowners close the gap between the insurer’s number and the contractor’s, and it’s routine, not adversarial.
Put the insurer’s estimate and your contractor’s side by side, line by line. Look for omitted items: ridge cap, drip edge, ice-and-water shield, valley metal, flashing, ventilation, decking, permits, disposal. Submit a written supplement listing each item, quantity, unit price, and supporting evidence, photos, measurements, specs, or code citations.
Request the insurer’s itemized estimate (often delivered as a PDF or in an estimating platform format) rather than a lump-sum number. You cannot supplement what you cannot see.
Reinspection, Appraisal, and Independent Review
If the supplement is rejected, request a reinspection by a different adjuster and ask for the request to be logged in the claim file.
If you still disagree on the amount of loss, check whether your policy includes an appraisal clause.
For coverage disputes, request a written appeal and escalate to a supervisor or the claims department before going outside the company.
Contractor Red Flags and Consumer Protections
Storm-chasing contractors are a real risk after hail and wind events, and a few warning signs protect both your claim and your home:
- Assignment of benefits (AOB). Some contractors ask you to sign over your claim rights so they can deal with the insurer directly and bill for the work. AOB arrangements have been restricted or regulated in a number of states because they can transfer control of your claim. Read anything titled “assignment,” “direction to pay,” or “work authorization” carefully before signing.
- Deductible waivers. An offer to “eat your deductible” or waive it entirely is a red flag, and in many states it is illegal, because you are contractually obligated to pay your deductible. A contractor who offers to absorb it is often inflating the estimate to compensate.
- Pressure to sign before inspection. Reputable contractors will let you wait for the adjuster’s inspection before you commit to a full replacement contract.
- No local license or insurance certificate. Ask for the license number and a certificate of insurance, and verify both with your state or local licensing authority.
Keep every letter, estimate, supplement, and record in one place. A clear paper trail lets any reviewer, internal appeals, appraisal, or a regulator, see what happened and what was left unresolved.
NAIC state insurance department directory and complaint resources
Booking a Free Roof Inspection and Claim Support Review With Atlanta Roof ProZ
Handling an insurance roof claim takes time, and the paperwork can feel overwhelming. At Atlanta Roof ProZ, we’ve spent over 18 years helping homeowners across the North Atlanta metro area document storm damage, understand their policies, and work through the claim process.
Our team can help you gather the right evidence, prepare clear documentation for your adjuster, and review the estimate for missing items. Please request a free estimate to get started on your claim.
Frequently Asked Questions
Can you claim a roof on insurance?
Yes, a homeowners policy can cover roof damage caused by a covered peril such as hail, windstorm, or fallen trees. Coverage depends on your policy form, whether the damage is sudden rather than from long-term wear, and whether any exclusions apply. Document the damage promptly, file with your insurer, and request a written explanation of any portion they decline to pay. Roof leaks caused by age or neglect are often excluded, so the cause of the damage matters as much as the damage itself.
How long does a roof insurance claim take?
Timelines vary by insurer, claim complexity, and weather volume after a storm. Settlements can take longer when supplements or disputes are involved. Keep a dated log of every call, email, and adjuster visit. Check your policy for the deadline to file a claim and for any proof-of-loss requirements, since missing these can jeopardize coverage regardless of how long the processing takes.
What happens if a roof insurance claim is denied?
A denial should come with a written explanation citing the policy language. Request a copy of your policy and the adjuster’s report, then compare the stated reason against your documentation. If the denial appears wrong, submit a supplemental claim with additional photos, a professional inspection report, and a contractor estimate. You can also request reinspection, ask for appraisal if your policy includes it, or contact your state insurance department for guidance on complaints.
Get Estimate: contact Atlanta Roof ProZ today to schedule your free roof inspection and claim support review.
